
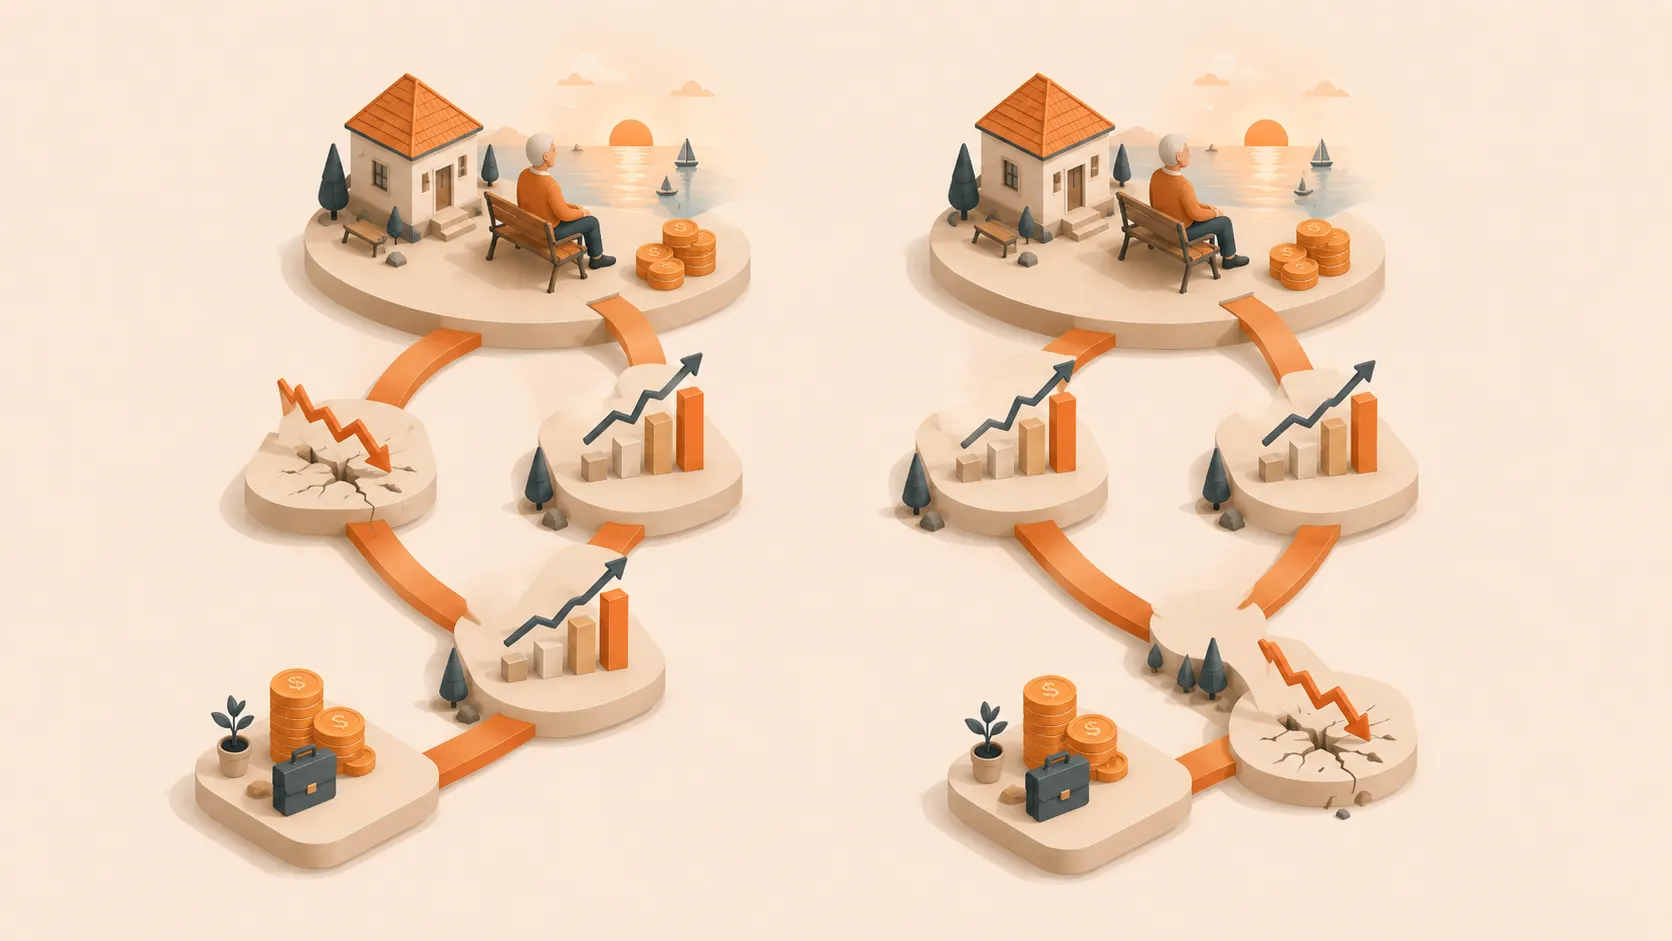
Two retirees can start with €1 million, withdraw €50,000 each year, and receive the same 30 annual returns. One can run out of money while the other finishes with €1.37 million. The difference comes from the order of the returns.
The order changes the outcome
Consider this synthetic sequence:
- one year at -40%;
- one year at -20%;
- one year at -10%;
- two years at +5%;
- 25 years at +8%.
Both retirees withdraw €50,000 at the end of each year. The sequence gives them the same long-run geometric average return of about 4%. We ignore inflation, taxes, fees, and asset allocation so the order remains the only variable.
The return (r_t) changes each year. The withdrawal (W) stays at €50,000.
If the crash arrives first, the balance falls to about €229,000 after five years and €43,700 after ten. The portfolio runs out during year 11. If the strong years arrive first, the balance reaches about €3.19 million after 25 years and ends near €1.37 million after the same later losses.
Without withdrawals, both sequences would finish at the same compounded value. Withdrawals change that result because assets sold after a decline cannot participate in the recovery. Vanguard documented the same mechanism in historical US data, where the retiree with the worse early sequence exhausted the portfolio sooner.[1]
Why early losses matter
Start with €1 million and a €40,000 withdrawal after the loss. A 10% fall leaves €860,000, a 20% fall leaves €760,000, and a 40% fall leaves €560,000. The next €40,000 then equals 4.65%, 5.26%, or 7.14% of the remaining balance.
The euro amount can stay flat while the percentage of the surviving portfolio rises. Track both figures after a major decline.
During accumulation, salary contributions can offset a poor return. During retirement, withdrawals can force you to sell into the decline. Later losses still matter, but fewer future withdrawals remain.
Buy flexibility before the crash
A cash reserve can fund planned spending while investments recover. If you spend €40,000 a year and hold €80,000 in retirement cash, you can cover two years without selling equities. Cash also has a cost, so test the reserve inside the whole portfolio.
Flexible spending can reduce forced sales. For example, you might cut €5,000 of travel spending for one year after the portfolio falls 20% below its planned path. Define the rule before retirement and test whether you would actually follow it.
Working one more year adds a contribution, avoids a withdrawal, and shortens the funding horizon. A partial year or part-time income can also reduce the first portfolio draw.
Separate emergency cash from retirement cashUse different assumptions for unexpected shocks and planned portfolio withdrawals.Stress-test the retirement date
Build several paths:
- Base return assumptions.
- A 20% first-year decline.
- A 40% first-year decline.
- Two weak opening years.
- High inflation with weak returns.
- A one-year retirement delay.
- A temporary spending cut after a drawdown.
Fignis can compare those branches on one timeline while you keep spending, pensions, and taxes visible. The useful question is, “What would I change after a bad start?”
The market chooses the return in your first retirement year. You choose the cash reserve, spending rules, retirement date, and portfolio allocation.
Review the portfolio before retirementConnect your asset allocation with the drawdowns you could face as withdrawals approach. Connect sequence risk with your withdrawal rateSee why a starting withdrawal percentage cannot replace a retirement cash-flow plan.