Data-driven articles for your biggest financial decisions
How Much Money Do I Need to Retire?
The usual answer comes from a 1998 study of a retiree with no pension, no taxes and a budget that never changes, which is almost certainly not you.
The Financial Value of Working One More Year
One extra working year can add contributions, postpone withdrawals, shorten the retirement horizon, and change how much spending your portfolio can support.
Pay Off the Mortgage or Invest? The Answer Changes Over Time
A mortgage-rate versus expected-return comparison leaves out liquidity, investment risk, retirement cash flow, taxes, and the time left on the loan.
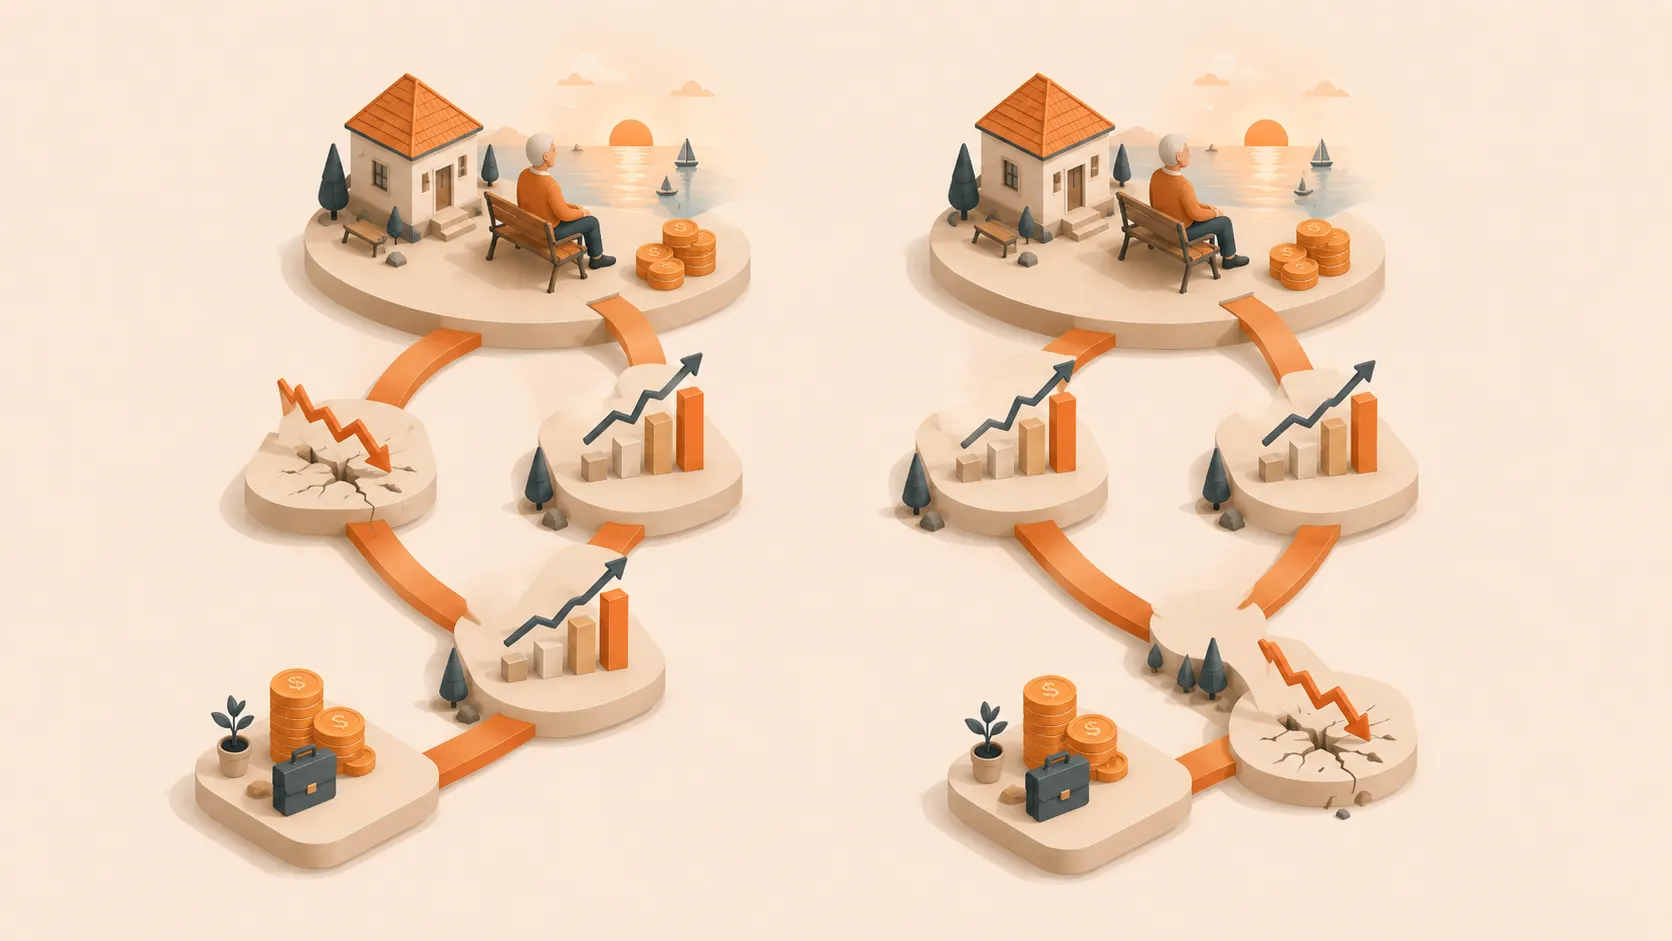
Retiring Into a Crash: How Much Does Timing Actually Matter?
Two retirees can start with the same wealth and earn the same long-run returns yet finish with different outcomes because withdrawals make return order matter.
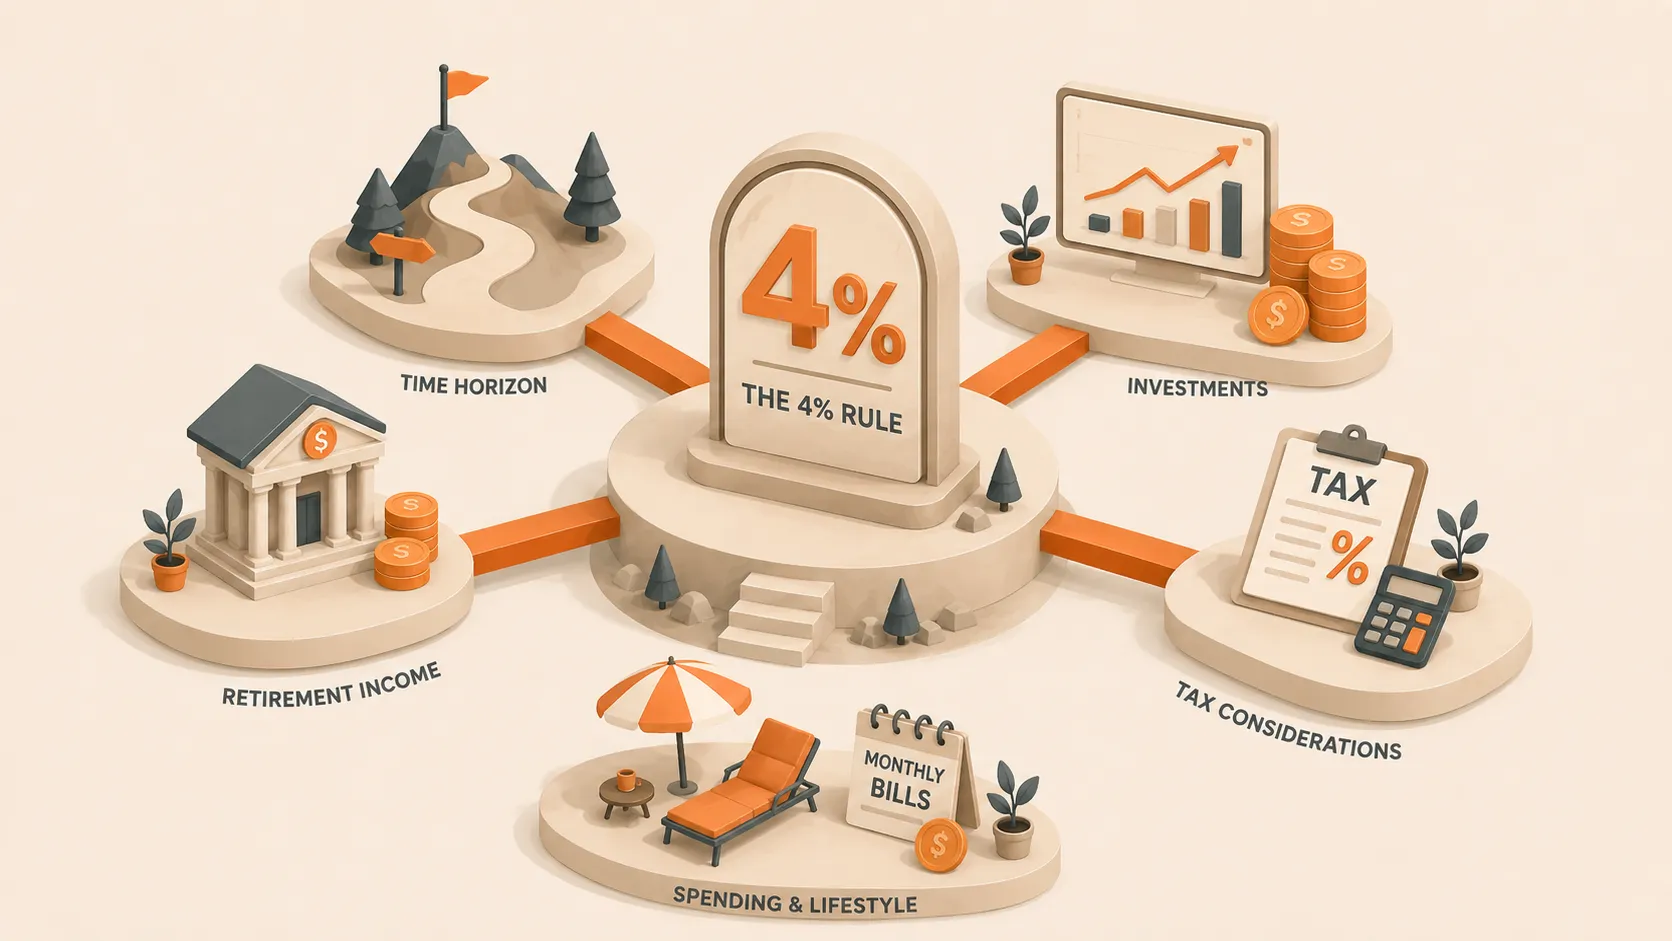
The 4% Rule: Build the Retirement Plan Around the Benchmark
A withdrawal rate gives you a useful retirement benchmark, but your horizon, spending flexibility, portfolio, taxes, and one-off expenses determine the plan around it.
Your FIRE Number Is Probably Wrong
A FIRE number can give you a useful target, but one number hides assumptions about spending, taxes, pensions, inflation, and the order of investment returns.
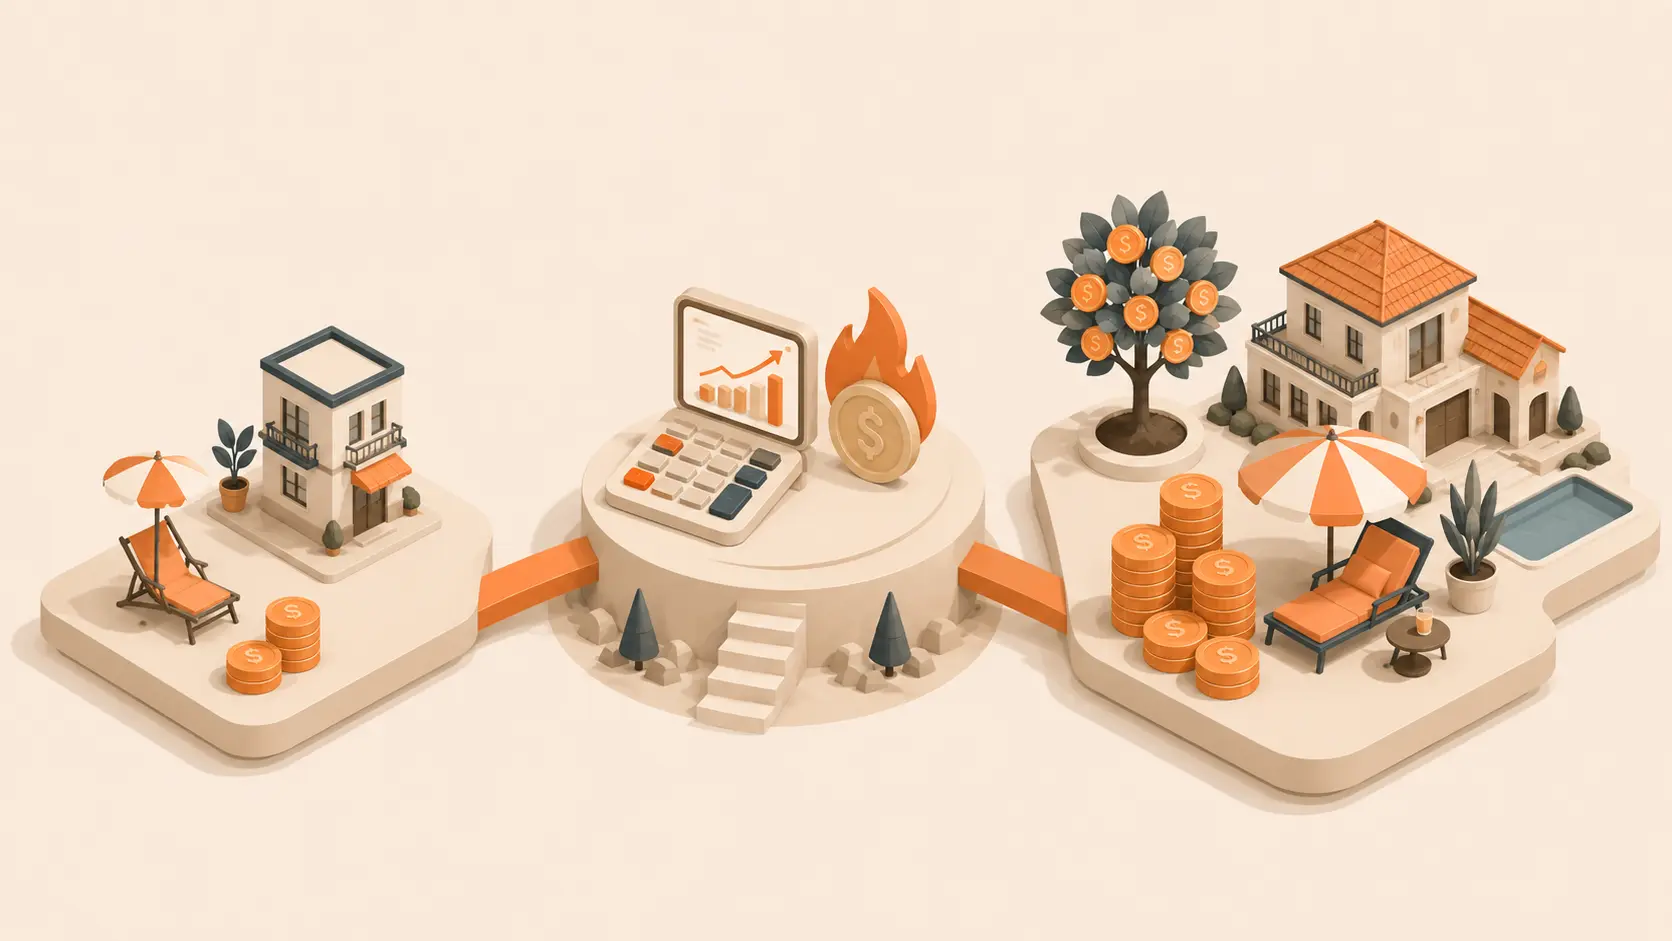
Lean FIRE vs. Fat FIRE: two very different ideas of enough
Lean FIRE trades future spending flexibility for earlier independence. Fat FIRE buys more room for change, but each extra year of accumulation costs time.
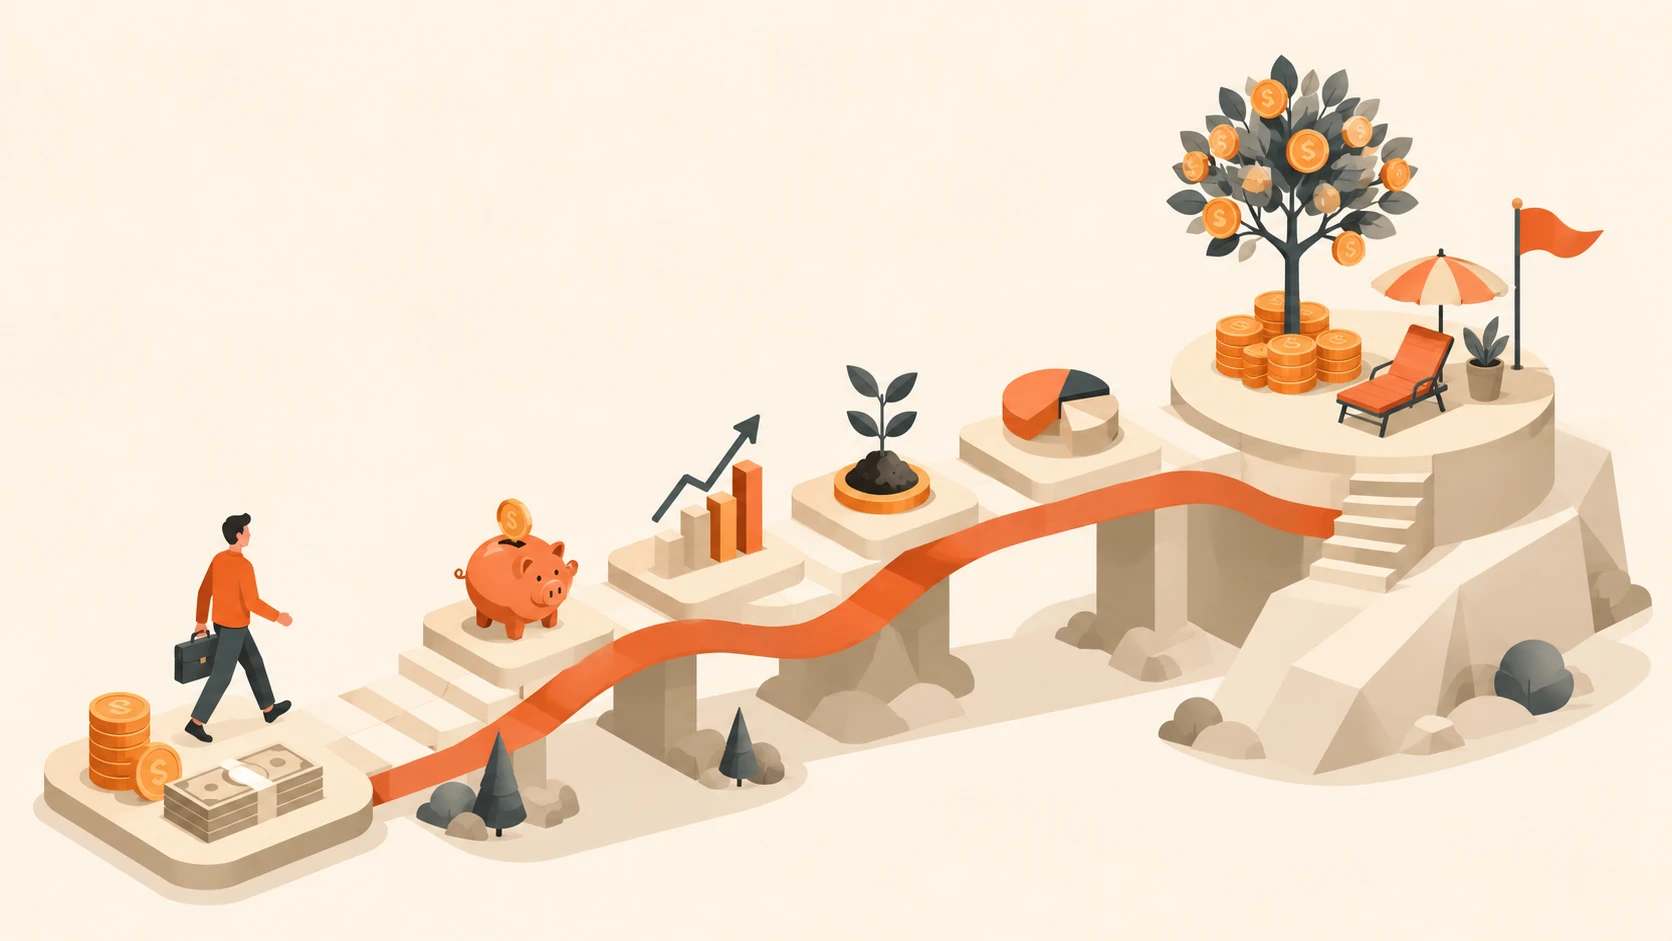
The Financial Independence Roadmap
Financial independence is the point where your money can cover your life. Learn how to calculate your number, focus on the variable that matters most, and bridge the gap if you get there early.
Portfolio Allocation Across Life Stages
The best portfolio is one you can hold through a crash without panic-selling. Here's how to set your allocation by decade and why where you hold things matters as much as what you hold.
How Much Emergency Fund Do You Actually Need?
The 3-to-6-month rule is too generic. Find the right number for your life by considering your job, health coverage, and the things that could realistically go wrong.
Retirement Planning by Decade
What matters at 30 is completely different from what matters at 55. Here's a decade-by-decade breakdown of what to focus on, what to watch out for, and the benchmarks that actually help.
Student Loan Repayment Strategies
Avalanche, snowball, refinancing, and forgiveness each work best in different situations. Use your actual numbers to find the strategy that saves you the most money and time.
Rent vs. Buy: A Decision Framework That Does Not Lie to You
Rent provides flexibility, while buying combines shelter, control, and a leveraged asset. The better choice depends on your timeline, local prices, cash drag, maintenance, taxes, and the cost of moving.